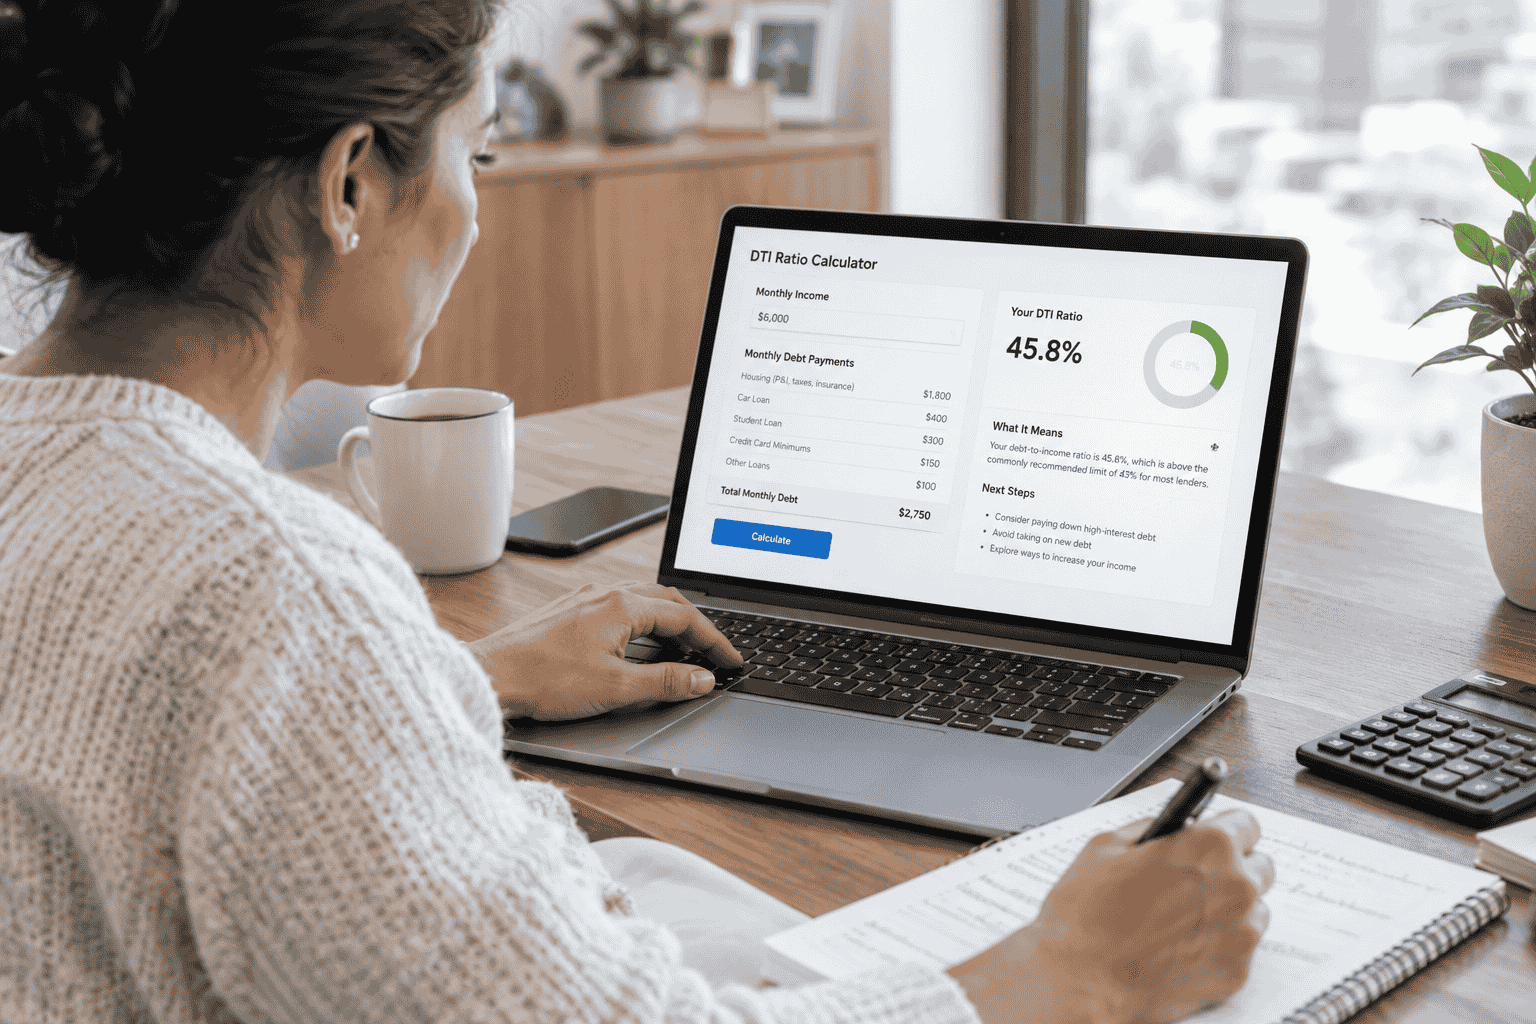
A DTI assessment tool turns two sets of numbers, what you earn and what you owe each month, into one percentage: your debt-to-income (DTI) ratio. Lenders use that percentage to judge whether you can handle another payment. The tool is only as good as the numbers you feed it, and most people feed it the wrong ones.
This guide shows you exactly what to enter, field by field, and how to read the result. It works with any DTI calculator, whether it comes from a bank, a credit bureau, or your own spreadsheet. By the end, you’ll know your ratio, understand how lenders are likely to see it, and have a plan to improve it.
The 60-second version
- Enter your gross (before-tax) monthly income.
- Enter the minimum monthly payment on each debt, plus your rent or planned mortgage payment.
- Leave out utilities, groceries, insurance premiums, and subscriptions.
- Divide total monthly debt by gross monthly income. Under about 36% is generally comfortable. Above roughly 43% to 50%, your options narrow, depending on the loan.
What a DTI assessment tool does (and doesn’t do)
Every DTI tool runs the same formula:
DTI = total monthly debt payments ÷ gross monthly income × 100
If you owe $2,000 a month in debt payments and earn $5,000 a month before taxes, your DTI is 40%. Lenders use this number to gauge your ability to repay a loan, because borrowers with high ratios tend to struggle more with consistent payments.
Two points save people a lot of worry:
- DTI does not affect your credit score. Credit reports don’t include your income, so score models can’t use it. A high DTI can still get you denied or priced higher, but it won’t drop your score.
- The tool gives an estimate, not a verdict. Lenders apply their own rules, verify your documents, and may count some items differently than a generic calculator does.
Front-end vs. back-end DTI
Many tools show two ratios, and they answer different questions.
- Front-end DTI (housing ratio): your housing payment alone, including principal, interest, property taxes, insurance, HOA fees, and mortgage insurance, divided by gross income.
- Back-end DTI (total ratio): your housing payment plus every other monthly debt, divided by gross income.
General-purpose calculators usually show only the back-end number. Mortgage calculators show both. For most mortgage programs, the back-end ratio carries more weight.
Before you start: gather your numbers
Ten minutes of prep prevents most errors. Pull together:
- Recent pay stubs, or your latest tax return and invoices if you’re self-employed
- The latest statement for every loan, credit card, and lease
- Your free credit report, which lists debts you might forget and their required minimums
- For a home purchase, an estimate of your planned monthly payment, including taxes, insurance, and HOA fees
Building your entries from a credit report gets you closest to what a lender will actually see.
Step 1: Enter your income
Use gross income, meaning the amount before taxes and deductions. Using take-home pay is the single most common mistake, and it makes your ratio look worse than it is.
What usually counts as income:
- Salary and wages
- Overtime, bonuses, and commissions, if they are consistent and documented
- Self-employment income, measured as net profit after business expenses, as shown on your tax return
- Rental income, which lenders often adjust for vacancies and expenses
- Pensions, Social Security, and disability benefits
- Child support or alimony you receive, if you can document it and it will continue
What usually doesn’t count: income you can’t document, one-time windfalls, and gifts.
Convert pay to a monthly figure
Tools ask for monthly income, so convert carefully:
- Annual salary: divide by 12
- Paid every two weeks: multiply one paycheck by 26, then divide by 12
- Paid weekly: multiply one paycheck by 52, then divide by 12
- Hourly: hourly rate × weekly hours × 52 ÷ 12
Watch the biweekly math. Multiplying a biweekly paycheck by two misses two paychecks a year and understates your income.
If your income varies
Lenders typically average variable income over a longer period, often two years for self-employed or commission-based earners. If your income has dropped recently, they may use the lower figure. For a quick personal check, average the last 12 months. For a lender-style check, use the lower of that average and your most recent year.
Step 2: Enter your debts
The rule is simple: enter the required minimum monthly payment on each recurring debt. Don’t enter balances, and don’t enter what you choose to pay each month.
| Include these | Leave these out |
|---|---|
| Rent, or your planned mortgage payment | Utilities, phone, and internet |
| Auto loans and leases | Groceries and dining out |
| Student loans | Health, car, and home insurance premiums |
| Personal loans | Streaming and other subscriptions |
| Credit card minimum payments | Everyday living costs |
| Child support and alimony you pay | Income taxes |
| Co-signed loans | Savings contributions |
Property taxes and homeowners insurance count only when they are part of your mortgage payment. Then they belong in the housing figure.
Special cases that trip people up
Credit cards. Enter the minimum payment on the statement. The balance doesn’t go into the formula, and neither does the larger amount you pay when you feel flush.
Student loans. Enter the payment from your statement. But if your loans are in deferment or on an income-driven plan with a $0 payment, mortgage lenders often still count a percentage of the balance, commonly 0.5% to 1%, depending on the program and your documentation. On a $30,000 balance, 1% means $300 a month. A generic tool will probably use your actual $0, so run a second scenario with the lender’s figure.
Nearly paid-off loans. Some mortgage guidelines let lenders exclude installment loans with ten or fewer payments remaining. Most tools don’t make that adjustment. If you have one, run the numbers both ways.
Co-signed debt. It counts against you even when someone else makes the payments. Mortgage lenders may exclude it if you can show that the other person has paid on time for 12 months.
Rent versus a new mortgage. When you’re buying a home, swap your rent for the proposed housing payment. Don’t count both.
Debt you’re about to take on. If you’re signing a car loan next month, include it. Lenders will see it.
Buy now, pay later. Include fixed installment plans, especially ones that report to credit bureaus. When in doubt, count them. A conservative estimate beats a surprise.
Step 3: Run the numbers
Example 1: a general DTI check
Say your gross income is $5,200 a month. Your monthly debts look like this:
| Debt | Monthly payment |
|---|---|
| Rent | $1,250 |
| Car loan | $390 |
| Student loan | $280 |
| Personal loan | $210 |
| Credit card minimums | $120 |
| Total | $2,250 |
DTI = $2,250 ÷ $5,200 × 100 = 43.3%
Example 2: a mortgage check with both ratios
Your gross income is $6,000 a month. The home you want would cost $1,700 a month, including principal, interest, taxes, insurance, and HOA fees. Your other debts total $800: a $450 car loan, a $250 student loan, and $100 in card minimums.
- Front-end DTI: $1,700 ÷ $6,000 = 28.3%
- Back-end DTI: ($1,700 + $800) ÷ $6,000 = 41.7%
The front-end number looks fine. The back-end number tells the fuller story, and it is the one most mortgage underwriting leans on.
Step 4: Read your result
Most tools show a color-coded gauge. The exact cutoffs differ from tool to tool, but this table captures the general picture:
| DTI range | What it generally means |
|---|---|
| Below 20% | Very comfortable. Lenders see plenty of room. |
| 20% to 35% | Manageable. Strong for most loans. |
| 36% to 43% | Acceptable for many loans, but lenders look harder at the rest of your file. |
| 44% to 50% | Possible with strong credit, savings, or a larger down payment. Fewer lenders and loan types. |
| Above 50% | Hard to qualify. Reduce debt or raise income first. |
What mortgage lenders typically allow
The old “28/36” rule of thumb, with housing under 28% and total debt under 36%, is a comfortable target, not a hard limit. Programs in 2026 allow more, depending on how strong the rest of your application is:
| Loan type | Front-end guideline | Back-end guideline | Notes |
|---|---|---|---|
| Conventional | No fixed limit | About 45%, up to 50% through automated underwriting | Manual underwriting is stricter |
| FHA | 31% | 43%, higher with strong compensating factors | Automated approvals can go beyond 43% |
| VA | None | 41% guideline | Lenders also weigh residual income and often approve above 41% |
| USDA | 29% | 41% | The tightest of the group |
These are general guidelines reported in 2026. Lenders often add their own stricter rules, and agencies update their guidelines, so confirm current limits with your lender.
Real borrowers often sit above the classic 36% line. CFPB figures reported by Credible put the median DTI around 37% for conventional borrowers, 44% for FHA, 42% for VA, and 36% for USDA. A ratio above 36% doesn’t shut the door. It means the rest of your file has to carry more weight.
Compensating factors that can offset a higher DTI include a strong credit score, a larger down payment, cash reserves, a stable employment history, and a modest increase over your current housing cost.
Step 5: Turn your result into a plan
You can improve DTI three ways: raise income, cut monthly payments, and avoid new debt. The tool’s best feature is the what-if test, so use it.
Take Example 1, where debts of $2,250 on $5,200 of income give a DTI of 43.3%. To reach 36%, you have two routes:
- Cut monthly debt to $1,872, which means removing $378 a month in payments.
- Raise gross income to about $6,250 with debts unchanged, an extra $1,050 a month.
In practice, you’ll often combine both. Here’s what works best.
1. Target payments, not balances. DTI measures monthly payments. Suppose you have a personal loan with a $2,800 balance and a $210 payment, and a car loan with a $14,000 balance and a $390 payment. Putting $2,800 toward the personal loan erases $210 from your monthly debt. Putting the same $2,800 toward the car loan leaves the required payment unchanged, so your DTI doesn’t move. Hunt for the debt with the highest payment relative to its balance.
2. Finish loans that are almost done. Clearing a loan with a few payments left removes the payment entirely, and some mortgage lenders ignore it once ten or fewer payments remain.
3. Pay off the cards and the small loan. In Example 1, clearing the $210 personal loan and the $120 in card minimums drops monthly debt to $1,920 and DTI to 36.9%.
4. Refinance or consolidate with care. A longer term lowers the monthly payment and improves DTI, but it can raise total interest. Compare the full cost, not just the payment.
5. Raise documented income. A raise, a second job with some history, or a co-borrower all help. A co-borrower’s debts count too, so check the combined math.
6. Pause new borrowing. Before a mortgage application, avoid new cards, car loans, and financed furniture.
7. Check your credit report for errors. A debt that isn’t yours, or a paid-off account still showing a balance, inflates your ratio. Dispute mistakes early.
One caution: don’t treat the maximum DTI a lender allows as the amount you should borrow. DTI ignores groceries, childcare, healthcare, and savings. A ratio that qualifies you can still feel tight once real life is added.
Seven mistakes that skew your result
- Using net pay. Enter income before taxes.
- Doubling a biweekly paycheck. Multiply by 26 and divide by 12.
- Entering balances instead of payments. The formula uses monthly payments.
- Counting living costs. Utilities, groceries, and subscriptions don’t belong.
- Forgetting debts. Co-signed loans, child support, payment plans, and buy now, pay later accounts often get missed. Use your credit report as a checklist.
- Ignoring the new payment. If you’re applying for a mortgage or car loan, include the payment you’re asking for.
- Treating the result as approval. Credit score, savings, job history, and loan type all matter too.
DTI outside the United States
The formula travels well, but the rules and the name don’t. In the UAE, for example, regulators use the term debt burden ratio (DBR). Central Bank rules cap the maximum DBR at 50% of gross salary and regular income from a defined source. Other countries rely on affordability assessments, debt service ratios, or their own formulas.
If you live outside the US, use a DTI tool to estimate your ratio, but check your bank or regulator for the exact limit and for what counts as debt. US-specific rules, such as FHA or VA guidelines and Fannie Mae’s student loan treatment, won’t apply.
What a DTI tool can’t tell you
A DTI result is one input. It does not show:
- Your credit score or credit history
- The interest rate you’ll be offered
- Your savings, down payment, or cash reserves
- Job stability and how long your income is likely to last
- Your real monthly budget
Two people with the same 38% DTI can look very different to a lender. One has steady income and six months of savings. The other has neither. Use the tool to see where you stand, then look at the whole picture.
Frequently asked questions
What is a good DTI ratio?
Below about 36% is generally considered manageable, and below 20% is comfortable. Many lenders approve higher ratios, especially for mortgages, when the rest of your application is strong.
Does DTI affect my credit score?
No. Credit reports don’t include income, so your score doesn’t reflect your DTI. Lenders still look at DTI separately when deciding whether to approve you.
Should I use gross or net income?
Use gross income, which is your pay before taxes and deductions. Net income overstates your DTI.
Does rent count toward DTI?
Yes, in most general DTI calculations. When you apply for a mortgage, lenders replace your rent with the proposed housing payment.
Do utilities and groceries count?
No. Utilities, groceries, phone bills, subscriptions, and insurance premiums are living costs, not debt payments. The exception is taxes and insurance that your lender collects as part of a mortgage payment.
Can I get a mortgage with a 50% DTI?
Sometimes. Conventional loans approved through automated underwriting can reach 50% with strong compensating factors, and FHA approvals can go high as well. Your options are narrower, and lenders will look closely at your credit, savings, and down payment.
How often should I check my DTI?
Check it before any major loan application and after any change in income or debt. Once a quarter works well if you’re actively paying down debt.
Your next step
Open a DTI tool and run three scenarios:
- Today: your current income and debts.
- With the new payment: add the mortgage, car loan, or other loan you’re considering.
- After your plan: remove the debts you intend to pay off or refinance.
Compare the three results. They show whether you can borrow now, how far you are from your target, and which debt to attack first. Then take your numbers to a lender or a nonprofit credit counselor to confirm how they will treat each item.
This guide offers general information, not financial advice. Lender rules and limits change, so confirm current requirements with your lender before making decisions.
Leave a Reply